Thursday, October 15, 2015

7 Tips for a Better LinkedIn Profile


7 Tips for a Better LinkedIn Profile
 
image: man relaxing in hammockWhether you're searching for a new job, looking for new referral connections, or just trying to look your professional best online, maintaining a LinkedIn profile is mandatory. Today, 93 percent of recruiters use social media sites to vet employees. Fortunately, a great profile doesn't take long to create with these seven tips:

Write an eye-catching headline. LinkedIn defaults the headline beneath your name to whatever your current job title says. Change it up to get noticed with action verbs and descriptive nouns. You may be a "marketing analyst," but a "10-year marketing veteran with a proven eye for viral content" is more powerful.

Use a professional headshot. According to Rick Sass, career coach at Lee Hecht Harrison, recruiters are 70 percent more likely to read your profile if you have one.

Take advantage of the background image. Showcase your interests like skiing, hiking or cooking. Avoid copyright issues by using personal or public domain photos.

Make your Summary special. The Summary section makes LinkedIn more powerful than a résumé. You can convey skills and experience with a readable narrative that also showcases your personality. At the bottom of your summary, include a section called "Specialties." Load this section with suitable keywords employers or referral partners might search. For example, if you work in advertising you might include: "Specialties: copywriting, social media and split-testing."

Highlight transferable skills. The Experience section is the closest thing to a résumé on LinkedIn. Don't use it to write a laundry list of duties you've performed for past employers. Confidently and conversationally highlight skills you developed in each position, and show how they apply to the job you want or the market you serve.

Quantify your accomplishments. There's credibility in numbers, so use specific data to demonstrate your expertise. Don't just say you're "a sales expert," include data on actual sales. If you've increased social media followers, give the percentage. If you don't have hard data, link to samples of your work in the Experience section.

Get a proofreader. According to Jobvite, spelling and grammar mistakes put off recruiters. Ask a friend or trusted colleague to check your spelling and grammar.

Creating a LinkedIn profile that helps you get noticed or hired isn't difficult. It takes a small investment of time now to create big dividends in the future. Schedule some time to update your profile this week!

Sources: Forbes, Success.com

Tuesday, October 13, 2015

Retiring Overseas

Imagine spending your retirement on an island in the Caribbean or in a historic European village. Thanks in part to a strong dollar, the dream of retiring abroad is becoming a reality for more Americans. According to a recent Bloomberg study, 615,000 Americans are receiving their Social Security checks outside of the United States. That’s a 57% increase since the year 2000. What’s driving that growth? A recent survey reported the top three reasons for retiring abroad as achieving a lower cost of living (87%), a simpler, less stressful life (82%) and better weather (74%). Survey respondents were also asked if their experiences lived up to their expectations. A whopping majority (85%) said they were happier living abroad.1 So why are some retirees happier on foreign shores? Commonly cited reasons are slowing down, becoming more present and mindful, and finding a strong sense of community. Many report that they’ve found a greater sense of meaning and purpose through making a positive difference in the lives of the local population. In fact, many expats have been pleasantly surprised to discover deep-seated connections with their new neighbors.

For the full article go to: http://www.ameriprise.com/content/files/AMP_20151006.HTML?CID=MOD_FMP_Pro_Oct_2015#2


Monday, October 12, 2015

New Changes for FHA and USDA Loans

Some of the FHA & USDA changes will effect a borrower's loan process.  Buyers should be prepared to answer these questions for their lenders and understand most need documentation.

1. Q. Are you using gift funds as a part of this transaction?  Change: Gift Funds must be sourced (able to verify with documentation where funds came from) even if they are wired.
 2. Q. Do you have student loan debt?  Change:  Student Loan Payments if deferred or not, will have to be counted either with the scheduled payment due w hen out of deferment, or 2% of the total amount (Have documentation of total amount or current payments).
3. Q.  Are you authorized to use any accounts not in your name?  Change:  Have to be counted in the debt ratio unless you can get 12 months of cancelled checks from the owner on the account (showing he has made all payments). You cannot remove the account from the borrower's credit report as an alternative to documenting the payments.
4. Q. Do you receive Alimony and/or Child Support? (Voluntary or Mandated) Change:  Now accepted by FHA with 6 months receipt to payments.
5. Q. Do you have any accounts that require you to pay off each month?  (i.e. American Express) Change:  Can be omitted from the debt to income ratio with 12 months evidence of the balance being paid in full and on time. If unable to document 12 months in full and on time payments, 5% of the balance will be included in the debt to income. Borrower must have sufficient assets verified to pay the account balance in full in addition to what is needed to close on the mortgage.
6. Q. Have you changed employers or type of employment in last 12 months?  Change: If employee has changed jobs more than 3 times in the last 12 months or has changed line of work, it will be more difficult to document stability.
7. Q. Have you been unemployed for more than 6 months?  Change:  Will require at least 6 months on the new job before applying for FHA loan.

8. Q. Have you had a Short Sale, Foreclosure, and/or Bankruptcy?:  Rules are different for different types of loans so be sure to let your lender know about them and dates when they 9. Q.  Are you applying for a  USDA Loan?:  Change: The Up Front Mortgage Insurance Permian is increasing to 2.75, effective October 1st

Thursday, October 8, 2015

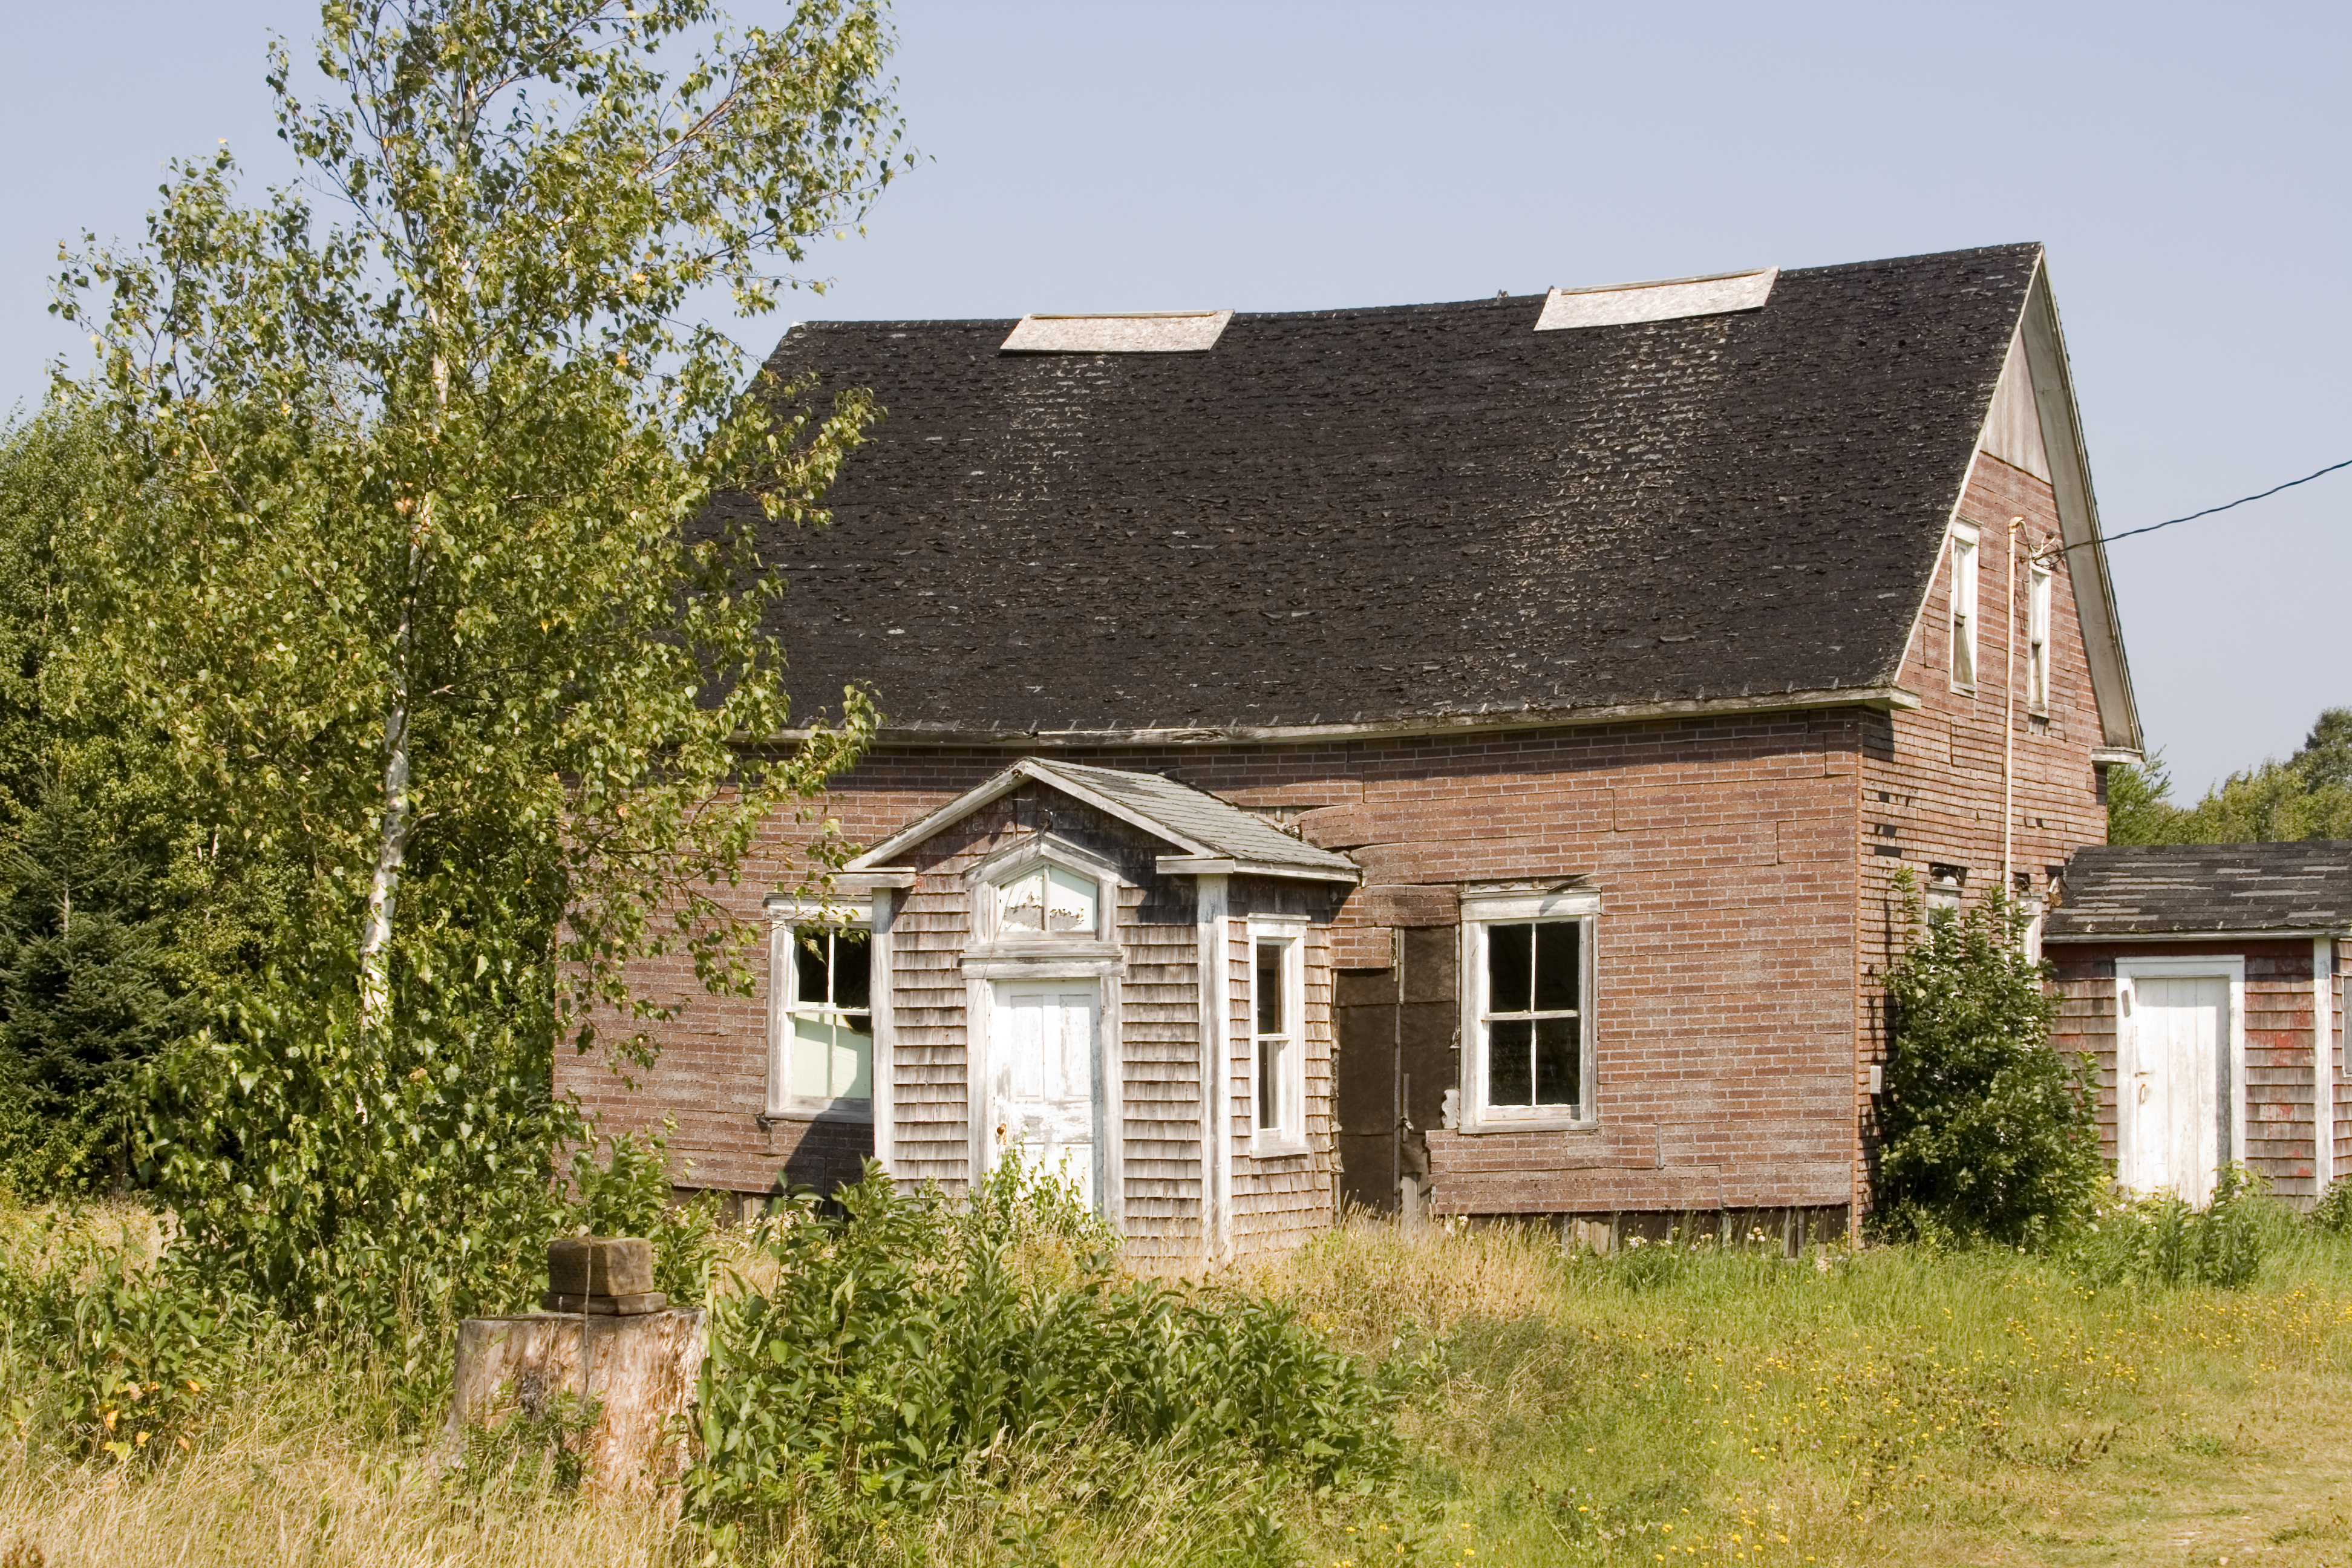
Is It Smart to Buy a Fixer-Upper

Is It Smart To Buy A Fixer-Upper As Your First Home?

fixerupperContributed by William Giakoumatos
Buying your first home can be very exciting. Among all the decisions you'll have to make when you seek that home is whether you want to buy one that's ready to move into and live in as is, or one that needs a little work. Many people buy fixer-uppers because of the lower cost, but sometimes those kinds of homes can end up costing you a lot more in the long run. Here are some things to consider when you're trying to decide whether it's smart for you to buy a fixer-upper or not.
1. What can you get in your price range?
Many first-time homebuyers are on tight budgets. They don't have a lot of money to spend, and they want to live in a good area. Overall, location is more important than the house, because the house can be changed. If you can't get into a good area without buying a fixer-upper, it may be worth considering. Just be sure you're really buying in a location you like and one that you want to remain in for a while so you can get the best deal and turn your house into a solid investment. Look at several houses, both fixer-uppers and finished, before deciding.
2. How handy are you, really?
There's a big difference between painting a room and fixing that plumbing leak. When you're considering a fixer-upper for your first home, make sure you're honest about your skill level. Don't buy into more than you can fix, or than you can afford to have fixed. By getting a good, thorough home inspection, you'll have a better idea of what kinds of improvements really need to be made. That can help you make the right decision based on the work you're able to do on the home.
3. How much savings do you have to use for repairs?
Repair budgets rarely get adjusted downward. Typically, it will cost more than you expect to repair a home. Even if you have plenty of savings, it's a good idea to get some repair estimates before committing to buying. That way, you'll have realistic numbers you can look at when you're trying to decide if that home is the right one for you. Surprise expenses can still crop up, but there will be fewer of them to contend with.
4. Do you have friends and family who can help?
If your uncle is a contractor and you have a niece in the design business, your odds of doing well with a fixer-upper just got better. When you have people who are in skilled trades and can help you work on your home, you can save a lot of money in labor costs and protect your investment more easily. It's not a requirement to have people like that in your family when you buy a house that needs work, but it can certainly help the process.
5. How long do you plan to live in the home?
Renovating a home takes time. If you don't plan to live in your first home for a long time, you might not want to buy something that requires a lot of work. You don't want to get into the middle of a renovation and decide that you need to move. It can be very difficult to sell a home that's in the middle of renovations, and you're likely to lose a lot of money in the process. Don't buy a fixer-upper you aren't really committed to keeping for years.
6. How is the market where you're looking?
If it's a buyer's market in your location, you may be able to get a great home for a much lower price. With that in mind, you could get into a home that needs less work and still not have to break your budget. Markets that favor the seller are going to have higher home prices, so buying a fixer-upper to get into a better neighborhood could be the way to go. There's nothing wrong with buying a house that needs some work, as long as you've done your homework and are prepared to handle the changes that need to be made.
7. Are the home's issues cosmetic or something more?
Cosmetic issues are things that can be lived with, even if you're not crazy about the way they look. If you have structural issues, though, you can't just leave those alone and not worry about them. They have to be fixed. Finding out which the home has and how much it will cost to correct any structural problems is very important if you're considering a fixer-upper for your first home.

Tuesday, October 6, 2015

What's Good, What's Not to Eat


11 Foods That Can Fool You
image: patio with a table and curtainsFiguring out which foods are good for you can be daunting. The biggest obstacle isn't evolving nutritional research, innumerable healthy food choices or even the countless diets. The main problem is that some foods don't provide the nutrition we think, either due to advertising or general misperception. Here are 11 foods to watch out for:

Salads are at their nutritional best when they contain more fresh, raw vegetables and lean protein than any other ingredients. As an example, the average Chicken Caesar has 700 calories and a whopping 46 grams of fat because the calories, carbs and fat grams from ingredients like cheese, croutons, egg or fried chicken can add up.

Salad dressings can add flavor, but they also add unwanted calories and fat. Average salad dressings may contain 75 calories and 6-8 grams of fat per teaspoon—and most of us pour more dressing on our salads than just a teaspoon. Here, less is certainly more, and homemade dressings (such as light vinaigrette) are the best options.

Rice cakes are the poster child for all things healthy, but they contain a large amount of high glycemic index carbohydrates that raise blood sugar levels. Elevated blood sugar levels can slow down the body's ability to burn fat. Adding a small amount of peanut butter or cheese, which contain healthy fats, can help mute the insulin response.

Chili has received a bad rap, mainly because "restaurant chili" usually contains inordinate amounts of fat, sodium and calories. Homemade chili is easy with a slow-cooker. Add vegetables and legumes to pack in vitamins, minerals and dietary fiber for a healthy, nutrient-dense meal that's also highly satisfying. Click here for 32 top-rated chili recipes from Cooking Light.

Crackers can make a great snack as long as you've verified the nutritional content. Many crackers actually contain more calories and fat, not to mention hydrogenated oils and sugar, than natural corn chips. Make sure to read the label!

Fruit juices are high in both sugar and calories, whether bottled or freshly squeezed. An 8-ounce glass of juice has nearly the calories and sugar content of the same amount of soda. Stick to either fresh-squeezed or natural juices containing 100 percent juice with no added sugar. Try diluting with spring water, too.

Nuts should be eaten in moderation if you're counting fat grams, but that doesn't mean they're an unhealthy food. Nuts are a fantastic source of low-carb protein and are high in fiber, so they curb hunger. Walnuts contain Omega-3 fatty acids, making them heart healthy as well.

Flavored oatmeal contains a fair amount of sugar, sometimes as much as 15 grams per packet. If you're one of those people who eats two packs at a time for breakfast, you may be consuming almost 30 grams of sugar before you even leave for work. Plain quick oats cook in roughly the same amount of time and give you more control over sweeteners.

Salsa is usually low in calories and fat; the sneaky ingredient, however, is salt. Fortunately, making your own is easy!

Muffins may taste delicious, but they are also loaded with calories, fat and sugar. Large muffins can contain up to 400 calories, which means nearly one-fifth of your caloric allotment on a 2,000 calorie-per-day diet. Whole grain and low-fat muffins are a better alternative, but make sure you read your labels regardless.

Protein bars were designed with "pro" athletes in mind. As a between-meal snack, they might provide more protein than the average person needs, and more calories than can be burned off. Some protein bars are more of a meal replacement than a snack, so get in the habit of checking the labels before you eat anything pre-packaged.

Friday, October 2, 2015

Rate's Stay Low


Fed Holds Its Benchmark Rate Steady
 

image: items on display for yard saleSeptember marked the start of football season for fans across the country. But investors and economists were focused on another team—the Federal Open Market Committee (FOMC), and whether it would hold its benchmark Federal Funds Rate steady.

What Is the Fed Funds Rate?
It's been more than nine years since the Fed raised the benchmark rate that banks and other depository institutions use to lend money to each other overnight. Despite some speculation to the contrary, the Fed held this rate steady at its September meeting instead of raising it. Why is this play important to homebuyers and homeowners? When the Fed Funds Rate climbs, home loan rates and lines of credit often increase as well, depending on the market and overall economy.

Will the Fed Funds Rate Rise This Fall?
Slowing global economies coupled with tame inflation were cited as two of the main reasons for the Fed's decision to hold the Fed Funds Rate steady in September. As we move further into October, the Fed will continue to monitor key statistics that signal improvement to the economy. In August, for example, consumer spending and retail sales were up, while housing starts have kept pace with more than one million new excavations each of the last five months.

However, the labor sector disappointed in August, as U.S. employers added 173,000 jobs, which was below expectations and the second lowest level in the past 19 months. Overall though, the labor market is stabilizing, adding an average of 212,000 workers each month through August of this year.

The Fed will consider a rate hike again at its meeting later this month before calling its next play. September data here at home and global conditions around the world will be key factors in its decision.

The Bottom Line
Home loan rates remain attractive and near historic lows. If you have any questions about the housing market and home loans, please don't hesitate to contact me.


Article from: You Magazine

Fall Soups


Easy Fall Soups
By Kirk Leins
image: chicken on a grillMaking soup doesn't have to be a marathon. Due to advancements involving key ingredients, many soups can be prepared in less than 30 minutes and for very little money.

The biggest improvement is canned (or boxed) stock. This product may never replace its homemade counterpart, but the various versions do a great job of getting a healthy dinner on the table, fast. Keeping canned broths (primarily chicken and vegetable) on hand will open up a world of quick, inexpensive and delicious soups.

Carrot Ginger Soup
(Serves 4)

1 pound carrots, peeled and roughly chopped
1 small onion, roughly chopped
1 tablespoon fresh ginger, peeled and chopped
1/4 teaspoon curry powder
4 cups chicken stock or water
1 cup orange juice
1/4 cup heavy cream
1 tablespoon unsalted butter
Salt and pepper

Combine butter and 1/4 cup of the chicken stock in a soup pot, and place over medium heat. Once the butter melts, add onion, ginger and curry powder. Once onions are tender, add remainder of chicken stock, orange juice and carrots. Bring to a boil and reduce to a simmer for 20 minutes. Using a food processor, blender or immersion blender, puree the mixture until smooth. Add cream, and return to simmer for 5 minutes. Season with salt and pepper and serve. A dollop of crème fraiche and snipped chives make an excellent garnish. Play around with the veggie-to-broth ratio depending upon the density of the vegetables and how thick or thin you like your soup.


Pumpkin Curry Soup
(Serves 4)

1 medium onion, chopped
2 medium leeks (white part only), chopped
1 clove garlic, chopped
1 15-ounce can of pumpkin puree
4 cups canned chicken stock
1 cup half and half
2 teaspoons curry powder
1/2 teaspoon cumin
1/4 teaspoon ground ginger
1/4 teaspoon cayenne pepper
1 bay leaf
2 tablespoons unsalted butter
2 tablespoons olive oil
Salt and pepper
Fresh cilantro

In a soup pot, melt butter together with oil until hot. Add onion, leeks and garlic, and sauté for 5 minutes. Add curry powder, cumin, ground ginger, cayenne pepper, and a dash of salt and pepper, and stir. Add pumpkin puree, chicken stock and bay leaf and stir to combine. Simmer for 15–20 minutes. Remove mixture from stove and process with an immersion blender until smooth. Return pot to stovetop and add half and half. Adjust seasonings, and simmer for another 5 minutes. Serve in bowls, and top with fresh cilantro.
pumpkin curry soup recipe card thumbnailcarrot ginger soup recipe card thumbnail

Kirk Leins has been cooking his entire life. No stranger to professional kitchens, he currently devotes most of his time to cooking instruction, food writing and producing television. Kirk also provides his services as a personal chef in and around the Los Angeles area. He has made several TV appearances on both the national and local level, and is the Executive Chef for YOU Magazine. Sign up for Kirk's free newsletter and cooking blog at www.NoTimeToCook.com.
 www.NoTimeToCook.com.